HOA & Condo Association
Association insurance reviews for New Mexico property managers
Master-policy reviews for New Mexico property managers serving HOA and condo boards. Discuss renewal options with BIG’s Albuquerque-based founder and team.
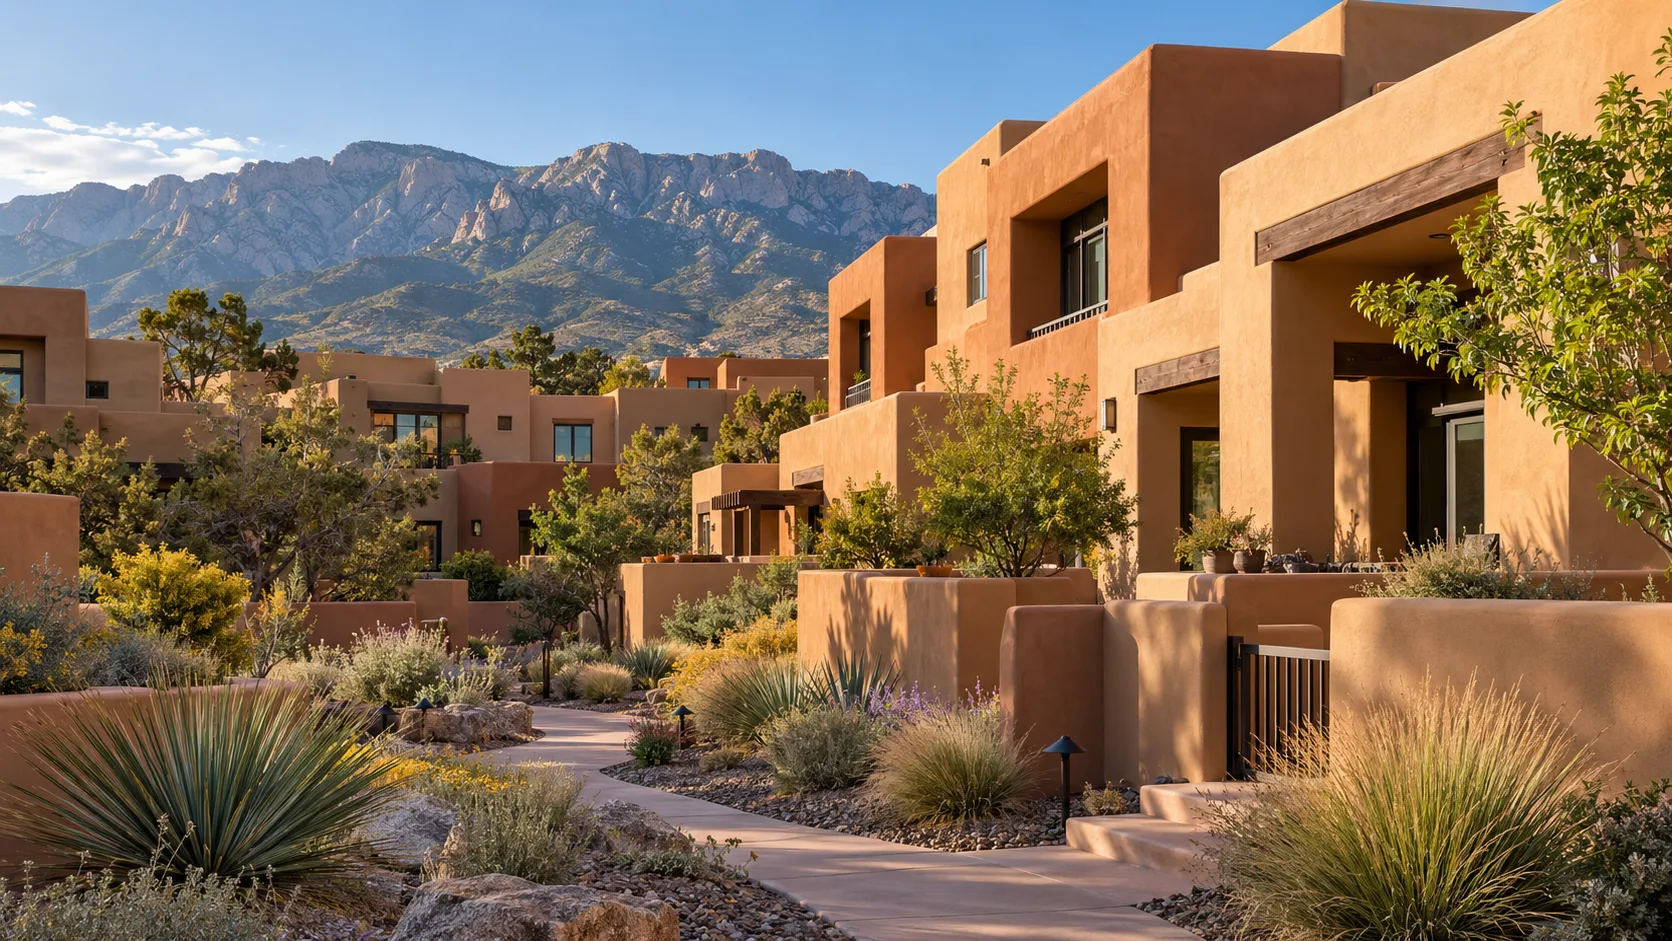
An insurance review that starts with the communities you manage
An Albuquerque condominium building, a Rio Rancho community with shared amenities and a Santa Fe association near a wildland area can require different insurance conversations. BIG helps New Mexico property managers and association boards review the property, policy terms and available options for each community.
Founder Darren Burch is based in Albuquerque. Call (612) 712-6407 or request an association master policy review, and tell us which account and deadline need attention first.
Identify the association’s responsibility at each location
Start with the association’s legal name, property addresses, unit count and renewal date. Share the declaration and bylaws, along with a schedule of buildings and common property. Some associations manage amenities or grounds; others have insurance responsibilities involving residential buildings. We need to understand that distinction before comparing proposals.
If your company also manages apartments or commercial buildings for separate owners, identify those properties separately. We can discuss a New Mexico commercial property review for those accounts. An HOA master policy should not be treated as the solution for every property in your management portfolio.
Put the address-specific information in front of underwriting
For each association, gather available roof dates, construction details, maintenance records, loss information and planned repairs. Where vegetation or wildland exposure is relevant, include information about access, defensible space and fire-protection measures. New Mexico’s insurance regulator provides wildfire-preparedness resources, but mitigation work does not guarantee eligibility or a discount from a particular insurer.
Ask about water, wind and hail provisions as well as fire coverage. If flood exposure needs review, address it separately rather than assuming the master property policy responds. The questions should follow the actual location and policy, not a blanket assumption about New Mexico properties.
A nonrenewal deadline needs a coordinated response
Send any nonrenewal notice with its effective date and the current coverage documents. Identify one person to coordinate the submission and another, if different, who can approve the board’s decision. Let us know which brokers or insurers have already reviewed the account.
When alternatives are available, ask for the premium, limits, deductibles, exclusions and outstanding requirements together. A proposal may still depend on inspections, repairs, applications or other underwriting conditions. Keep the existing policy in place until replacement coverage has been confirmed.
Keep the manager’s business insurance in the conversation
Your management agreement may create insurance obligations for your own company as well as for the association. Send those requirements if you want a separate review of the management business’s coverage. We should not assume that an association master policy or a certificate provides all of the protection your company needs.
Start with one upcoming renewal
You do not need to organize every account before contacting us. Start with the association name, property address, your role and the renewal date. We can explain what is needed to review that account and discuss additional communities as the information becomes available.
See our New Mexico HOA master policy page and Albuquerque commercial insurance page. Coverage availability, pricing and terms depend on the property and underwriting.
Sources
- New Mexico Office of Superintendent of Insurance: wildfire preparedness (checked 2026-10-06)
Related resources
Continue reading
Commercial insurance in Albuquerque, starting with your business
When you are buying a building, signing a lease or coming up for renewal, you need someone to help you work through the insurance. BIG's founder, Darren Burch, is based in Albuquerque, and our team works with New Mexico business owners by phone and online.
Read more →
What should a New Mexico building owner know about commercial property insurance?
BIG is licensed in New Mexico and writes commercial property insurance statewide. New Mexico buildings are priced differently because of regional construction (adobe, stucco, flat roofs), wildfire exposure in the north, monsoon hail, and arroyo flooding. After the 2022 and 2024 fire seasons, carriers raised rates, added percentage deductibles, and non-renewed exposed properties. A review checks the insured value, the rate, and the deductibles, and shops the building across more than 50 carriers and wholesale markets.
Read more →