Locations
Commercial building insurance quote in Arizona
Need a quote on an Arizona commercial building? Compare roof terms, wind and hail deductibles and renewal notice rights with a licensed Arizona agency.
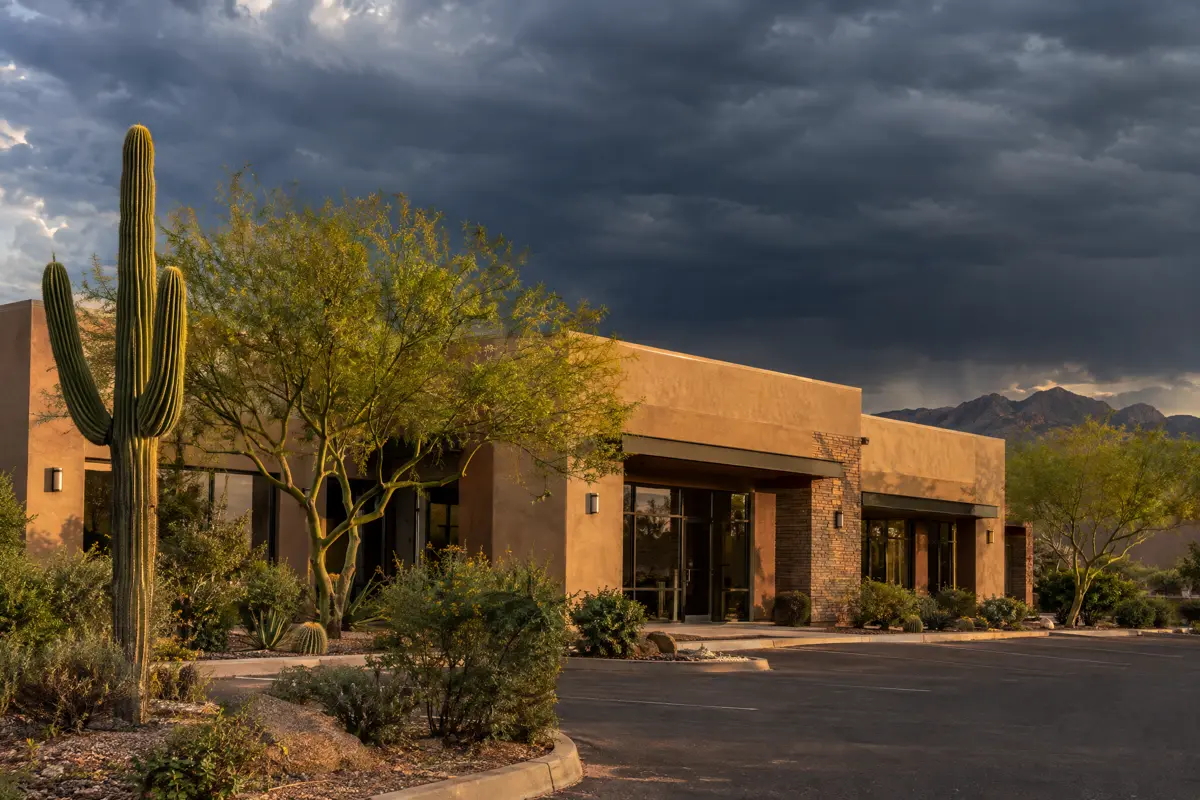
If you own an apartment, retail, office, industrial or mixed-use building in Arizona and want a quote, start with three things: your renewal date, the age and type of your roof, and your loss history. Burch Insurance Group compares the commercial property options available for buildings in Phoenix, Tucson, Flagstaff and the rest of the state, and shows you how monsoon wind and hail, and wildfire in the high country, affect the terms you are offered.
or call 612-712-6407. Licensed in Arizona.
How much notice does my Arizona insurer have to give before nonrenewal or a big increase?
Arizona law sets notice rules for commercial property, commercial liability and commercial multi-peril policies written by admitted insurers. Under A.R.S. 20-1676, an insurer that will not renew must send notice at least 45 days before the end of the policy period. Under A.R.S. 20-1677, an insurer must give written notice at least 30 days before expiration of a premium increase, a change in deductible, a reduction in limits or a substantial reduction in coverage. If the insurer misses that 30-day notice, the existing coverage stays in effect until the notice is given or replacement coverage takes effect, whichever comes first.
These rules do not apply to every policy. The same article excludes surplus lines insurance, excess policies and policies covering multistate location risks. If your building is insured in the surplus lines market or on a multistate schedule, read your policy's own notice terms.
Forty-five days is not much time to market a building. We suggest starting 90 days before renewal, especially if the roof is older or you had a recent claim.
How does monsoon season affect a Phoenix or Tucson building quote?
The National Weather Service office in Tucson defines the monsoon as June 15 through September 30. It issues severe thunderstorm warnings for damaging winds of 60 mph or greater and notes that the strongest straight-line gusts can exceed 100 mph. Large hail is hail greater than one inch across, and the Weather Service says golf-ball-size hail is more common in the mountains and mid elevations. Its review of the 2025 season in the Phoenix area reported microburst wind damage and large hail during a late September storm system in south-central Arizona.
For a commercial building, that shows up in underwriting as questions about the roof. Expect to be asked:
- The roof type, such as built-up, modified bitumen, single-ply membrane, foam or tile, and the year it was installed or recoated
- Whether rooftop HVAC units, solar panels and parapets are secured, and when they were last inspected
- Whether the roof is valued at replacement cost or actual cash value on the quote
- Whether there is a separate wind or hail deductible, and whether it is a flat dollar amount or a percentage of the building value
Two quotes with the same premium can pay very differently after a monsoon storm. Compare the roof settlement terms and the deductible, not only the price.
What about wildfire for buildings in Flagstaff and the high country?
The City of Flagstaff runs a wildland fire management program that includes Wildland Urban Interface code enforcement, Firewise property assessments and hazardous fuel thinning and burning. If your building is near forest or open land, ask the city whether its Wildland Urban Interface requirements apply to your property, and keep records of any assessment or clearing work.
Underwriters will ask about distance to brush or timber, roof covering, vents, how close vegetation is to the walls and how far the nearest fire station is. Lightning during monsoon season can also start brush fires, which the Tucson Weather Service office lists among monsoon hazards, so desert-edge properties around Tucson and Phoenix may get similar questions.
What else drives the price on an Arizona commercial building?
Beyond weather, the building's own facts carry the most weight: construction type, occupancy, sprinklers and alarms, the age of electrical, plumbing and roofing, vacancy, the value you insure and your losses over the last five years. A current replacement cost estimate matters because an undervalued building can trigger a coinsurance penalty on a partial loss.
Take a fictional 14-unit retail strip in Mesa with a 16-year-old foam roof that was recoated four years ago. At renewal the owner sends us the current policy, the recoat invoice, photos of the rooftop units, the rent roll and five years of losses. With that file we can show underwriters that the roof was maintained and ask each one how they would settle a roof claim. This is an illustration, not a promise of a particular result for your building.
Questions Arizona building owners ask us
Does my commercial property policy cover monsoon wind and hail? Most commercial property forms include windstorm and hail, but check for a separate wind or hail deductible, cosmetic damage exclusions on metal roofs and actual cash value settlement on older roofs.
My renewal with a higher premium arrived 20 days before expiration. What happens? If your policy is with an admitted insurer and falls under A.R.S. 20-1677, the existing coverage continues until proper notice is given or replacement coverage takes effect. Call us so we can look at the notice and your options.
Can you quote a building in Flagstaff near the forest? Often yes. A complete submission with mitigation records, roof details and photos gives underwriters what they need to consider it.
Do I need an agent with a local office? No. Burch Insurance Group is licensed in Arizona and works with Arizona owners by phone and online.
Start with your renewal date
Send the renewal date or any nonrenewal notice, the current policy, the roof details and what you know about the building. Keep your current policy in place until replacement coverage is confirmed in writing. Our guides to coinsurance and agreed value and roof terms and hail deductibles at renewal explain two parts of a quote that often matter most after a storm.
Request a commercial property quote, or call 612-712-6407.
Burch Insurance Group is licensed in Arizona.
Sources
- A.R.S. 20-1676, notice of nonrenewal (commercial lines) (checked 2026-11-04)
- A.R.S. 20-1677, notice of premium or coverage changes (checked 2026-11-04)
- A.R.S. 20-1671, scope of commercial cancellation and nonrenewal article (checked 2026-11-04)
- National Weather Service Tucson, Monsoon Safety (checked 2026-11-04)
- National Weather Service Phoenix, 2025 Monsoon Season Review (checked 2026-11-04)
- City of Flagstaff, Wildland Fire Management (checked 2026-11-04)
Related resources
Continue reading
Commercial Property Coinsurance and Agreed Value
Understand coinsurance on a commercial building quote, why a partial loss can be reduced, and what to ask about agreed value before choosing a policy.
Read more →
Commercial Roof Terms at Renewal: Hail Deductibles and ACV
A renewal can add a percentage wind or hail deductible, actual cash value roof settlement or a cosmetic damage exclusion. See what each means before you renew.
Read more →