Commercial Property
What changed in the roof terms on my commercial property renewal?
A renewal can add a percentage wind or hail deductible, actual cash value roof settlement or a cosmetic damage exclusion. See what each means before you renew.
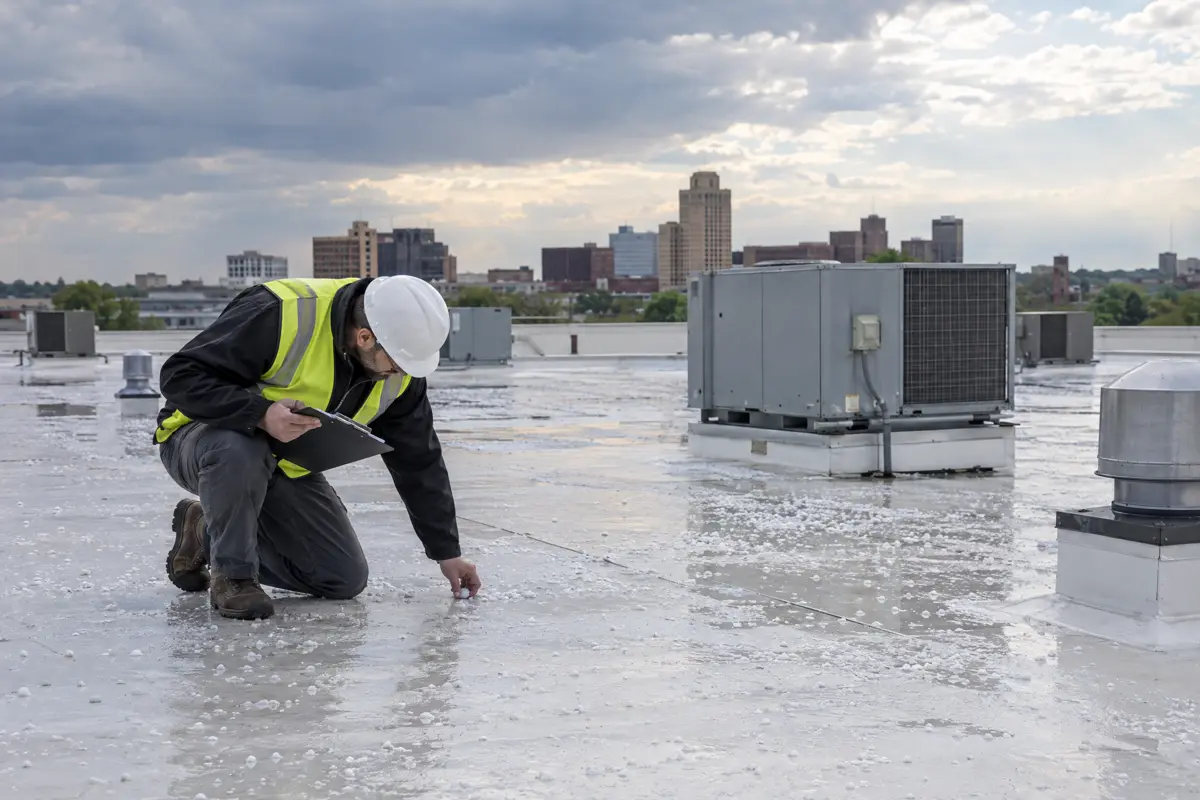
A commercial property renewal can look familiar on the first page and still change how a roof claim would be paid. Three changes deserve a close look: a percentage wind or hail deductible, roof damage settled at actual cash value, and an exclusion for cosmetic damage. Each can move a large part of a roof loss back to you, even when the premium barely changes.
Burch Insurance Group helps apartment and commercial building owners read these terms before the renewal date, including owners in Minnesota, New Mexico and California. Send us the current policy and the renewal offer. We can explain what changed and look at available alternatives across a broad spectrum of markets, without assuming another insurer will offer broader terms or a lower price.
A percentage deductible is calculated from value, not a flat amount
A flat deductible is a fixed dollar amount. A percentage wind or hail deductible is calculated from the value used by the policy. Common percentages are 1%, 2% or 5%.
For a fictional building insured for $3 million, a 2% wind or hail deductible would be $60,000 for that building in that storm. That is a hypothetical calculation, not a quote. Many forms apply a separate deductible to each damaged building in each storm, so a hailstorm that damages three buildings can produce three deductibles. On a blanket policy, the percentage may be applied to the value reported for the damaged building on your statement of values rather than to a building limit.
Ask which value the percentage uses, whether it applies per building and per occurrence, and whether a minimum dollar amount applies. Then decide whether you could pay that amount after a storm.
Actual cash value can mean depreciation on an older roof
Replacement cost pays to repair or replace damaged property with new materials of like kind and quality, subject to the policy terms. Actual cash value subtracts depreciation. On a newer roof the difference may be small. On a roof near the end of its expected life, depreciation can be most of the cost.
Some renewals add an endorsement that settles roof losses at actual cash value even though the rest of the building stays at replacement cost. Look for a separate roof provision in the renewal, and ask whether it applies to every roof or only to roofs past a certain age.
A cosmetic damage exclusion can leave dented surfaces unpaid
Some policies exclude cosmetic damage to roofs. These provisions generally describe marring, pitting or denting that does not affect the roof's ability to keep water out. Hail that dents metal panels without causing a leak is the typical example.
If your building has a metal roof, siding or rooftop equipment that hail can mark, ask whether the renewal adds this kind of exclusion and how it is worded.
Read the roof terms with the rest of the renewal
Roof provisions interact with the building limit, valuation, coinsurance and the deductibles for other causes of loss. A lower premium with a new roof endorsement is not necessarily a better offer than a higher premium without one. Our guide to coinsurance and agreed value covers another term that can reduce a partial-loss payment.
Roof records help underwriting see the building accurately. Gather the roof type, installation year, coating or repair invoices and any inspection reports. For an older building, see insurance for older commercial buildings. Apartment owners can use our apartment renewal comparison guide.
Questions owners ask about roof terms at renewal
Can a renewal switch my roof to actual cash value? Yes. It usually appears as a new endorsement or a change in the forms list. Compare this year's forms list with last year's, and ask whether the change applies to every roof or only older ones.
Is a percentage hail deductible negotiable? Sometimes. Options depend on the building, the roof's age and condition, the location and the markets willing to write it. We can ask for alternatives, such as a different percentage or a flat amount, but there is no guarantee one is available.
Does a cosmetic damage exclusion apply if hail causes a leak? These provisions are generally written for damage that does not affect the roof's ability to keep water out. Damage that lets water in is usually treated differently, but the policy wording controls.
Ask BIG to compare the renewal before it takes effect
You do not need to interpret every endorsement yourself. Send the current policy, the renewal and the renewal date. We will point out roof-related changes, explain what they would mean after a storm and discuss the options available for your building.
Request a commercial property review, or call 612-712-6407.
Sources
- Insurance Journal, "The Problem(s) With Hail Claims, Part 2," June 17, 2024 (checked 2026-10-26)
- ISO CP 03 21 windstorm or hail percentage deductible, form summary (checked 2026-10-26)
Related resources
Continue reading
Commercial Property Coinsurance and Agreed Value
Understand coinsurance on a commercial building quote, why a partial loss can be reduced, and what to ask about agreed value before choosing a policy.
Read more →
Insurance for Older Commercial Buildings
Compare insurance for an older commercial building using documented updates, roof and valuation terms, ordinance or law coverage and deductibles.
Read more →
Apartment Insurance Premium Increase? Compare Options
Compare apartment building insurance after a premium increase. BIG reviews available markets, roof terms, deductibles and rental income coverage.
Read more →