Locations
Commercial building insurance quote in Idaho
Need a quote on an Idaho commercial building? Prepare for questions on snow load, wildfire exposure and winter freeze, and know Idaho's nonrenewal notice rules, which lengthen to 60 days for policies effective on or after January 1, 2027.
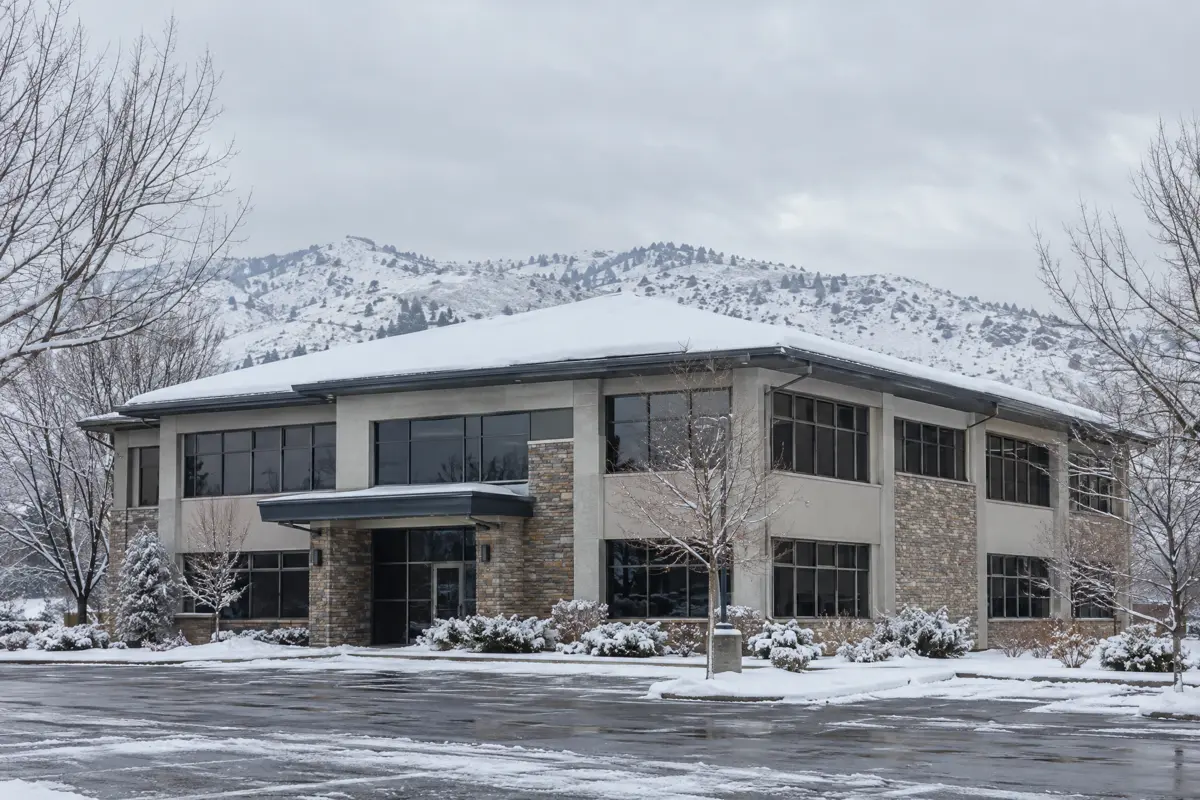
If you own an office, retail, warehouse, apartment or mixed-use building in Idaho and need a commercial property quote, start with the roof, the snow and the renewal date. Idaho underwriters look closely at roof age and condition, how the building handles heavy snow, wildfire exposure near the property and how the building is heated and watched in winter. Burch Insurance Group reviews those details with you, takes the building to the markets that fit it and shows you what each quote covers and leaves out.
or call 612-712-6407. Licensed in Idaho.
How much notice do I get if my Idaho building is nonrenewed?
Under Idaho Code section 41-1842, an insurer that will not renew a commercial property, commercial liability or commercial multiperil policy has to send written notice before the policy expires. Idaho changed the rule in 2026. House Bill 562 raises the nonrenewal notice from 45 days to 60 days, and raises the notice for most cancellations other than nonpayment from 30 days to 60 days. Cancellation for nonpayment of premium stays at 10 days.
The Idaho Department of Insurance says in Bulletin 26-12 that the longer notice periods apply to policies issued or renewed with an effective date on or after January 1, 2027. Excess and surplus lines policies are among those the section excludes, so if your building is written on a surplus lines policy, read that policy's own cancellation and nonrenewal terms.
Use the notice period. An owner who starts the day the notice arrives has time to gather building details, let several underwriters look and compare written terms before the old policy ends. An owner who waits until the last two weeks has fewer choices.
Why snow load matters on an Idaho building quote
Heavy snow is a real building risk in Idaho, not only in the mountains. In February 2017, Ada County, which includes Boise, was added to a state disaster declaration for winter storm damage that also covered Canyon County, home to Nampa and Caldwell. The Idaho Office of Emergency Management reported record snowfall that used up snow removal resources and widespread roof collapses on both commercial buildings and homes.
For a quote, underwriters want to know:
- Roof type, age and the date of the last replacement or major repair
- Whether the roof is flat or low slope and where snow drifts against parapets, rooftop units or taller additions
- Who clears snow from the roof and how often during a heavy winter
- Whether roof drains and gutters are kept clear so meltwater does not back up and refreeze
A clean roof report and a written snow removal plan do not guarantee a quote or a lower price. They do help an underwriter see the building accurately instead of assuming the worst.
Wildfire exposure around Coeur d'Alene, Idaho Falls and the Boise foothills
Idaho's 2023 State Hazard Mitigation Plan lists severe weather, flood and wildfire as the top three local hazards in the state. In the plan's county summary, Kootenai County, home to Coeur d'Alene, rates wildfire and severe storms high. Bonneville County, home to Idaho Falls, also rates wildfire and severe storms high. Ada and Canyon counties rate severe storms high.
If your building sits near timber, open range or brush, expect questions about the distance to vegetation, roofing material, vents, nearby structures and access for fire crews. Cleared vegetation and documented maintenance give the underwriter something concrete to work with.
Winter freeze and vacant space
Frozen pipes and the water damage that follows a thaw are a common winter claim for commercial buildings in cold climates. Underwriters will ask how the building is heated, whether there is a low temperature alarm or monitored sprinkler system, and whether any space is vacant. Many commercial property forms limit coverage when a building has been vacant for a set period, so tell us about empty suites or a building between tenants before we quote, not after a loss.
Earthquake is a separate decision
The state plan also rates earthquake high for Canyon and Kootenai counties and uses Idaho Falls as an example of the damage a large quake could cause. Standard commercial property policies generally exclude earthquake. If you want it, or your lender requires it, we can quote it separately so you can see both costs together.
Questions Idaho building owners ask us
Will an older roof keep me from getting a quote? Not always, but it often changes the terms, such as a higher deductible or roof coverage settled at actual cash value. Roof photos and repair records help.
My policy is up in December 2026. Does the new 60 day notice apply? The Department of Insurance says the longer notice applies to policies issued or renewed on or after January 1, 2027. Before then, the 45 day nonrenewal notice applies to covered commercial policies.
Does snow on the roof count as a covered loss? It depends on the policy wording. Many commercial forms cover collapse caused by the weight of snow or ice, with conditions. Ask to see the collapse and roof wording in each quote.
Do I need a local office? No. Burch Insurance Group is licensed in Idaho and works with Idaho owners by phone and online.
Start with your next deadline
Send the renewal date or nonrenewal notice, the current policy, five years of losses and what you know about the roof, heating and occupancy. Keep your current policy in force until replacement coverage is confirmed in writing. Our guides to coinsurance and agreed value and roof terms, renewals and hail deductibles explain terms that often change the value of a quote.
Request a commercial property quote, or call 612-712-6407.
Burch Insurance Group is licensed in Idaho.
Sources
- Idaho House Bill 562 (2026), amending Idaho Code 41-1842 and 41-2401 (checked 2026-11-04)
- Idaho Department of Insurance Bulletin 26-12, revised nonrenewal and cancellation notices (checked 2026-11-04)
- Idaho Office of Emergency Management, Ada and Boundary counties added to state disaster declaration, February 9, 2017 (checked 2026-11-04)
- Idaho State Hazard Mitigation Plan 2023, chapters 1 and 2 (checked 2026-11-04)
Related resources
Continue reading
Commercial Property Coinsurance and Agreed Value
Understand coinsurance on a commercial building quote, why a partial loss can be reduced, and what to ask about agreed value before choosing a policy.
Read more →
Commercial Roof Terms at Renewal: Hail Deductibles and ACV
A renewal can add a percentage wind or hail deductible, actual cash value roof settlement or a cosmetic damage exclusion. See what each means before you renew.
Read more →